Credit cards offer many rewards to attract customers, but two of the most common benefits are cashback and reward points.
At first glance, cashback appears simple: spend money and get some money back.
Reward points can look more attractive because they may be redeemed for travel, vouchers, products or other benefits. But a reward point does not always have the same value as ₹1, and some cards impose redemption fees, limits, category exclusions or monthly caps.
For example, HDFC Bank’s current card terms show that reward-point value can differ significantly between cards and redemption methods, while some cards also impose earning or redemption caps.
So the real question is not:
“Cashback or reward points?”
It is:
“Which benefit gives me the highest effective value for the way I actually spend and redeem?”
Quick Comparison
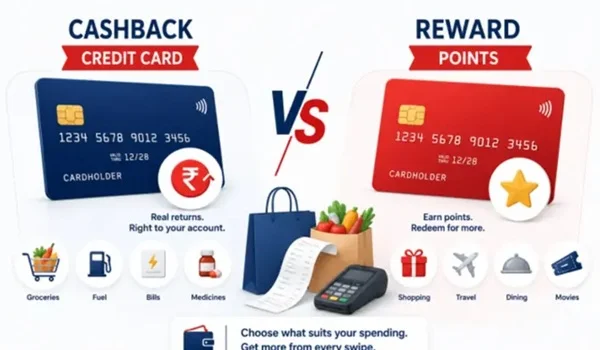
| Factor | Cashback | Reward Points |
| Benefit Type | Direct monetary benefit | Points accumulated from spending |
| Ease of Understanding | Very easy | Requires valuation |
| Redemption | Usually statement credit/cashback | Vouchers, products, travel or cashback |
| Value | Usually fixed | Can vary by redemption |
| Flexibility | High | Depends on card |
| Expiry Risk | Usually lower | Can apply depending on card |
| Redemption Fees | Usually limited/none, depending on card | May apply |
| Best For | Everyday spending | Travel/rewards optimisation |
| Main Risk | Caps/exclusions | Poor redemption value |
What Is Credit Card Cashback?
Cashback is a credit-card reward in which a percentage of eligible spending is returned to the cardholder.
For example, suppose a card provides:
2% cashback
and you spend:
₹10,000
Your cashback would be:
₹10,000 × 2% = ₹200
If the cashback is credited directly against the card statement, the benefit is straightforward.
Some cards may define cashback as cashpoints or a similar reward mechanism rather than an immediate reduction in the bill. Therefore, check the card’s terms before assuming when and how the cashback is credited.
For example, HDFC Bank’s published terms for one card describe CashPoints being redeemable as cashback against the statement at a specified conversion rate.
Advantages of Cashback
Cashback is attractive because:
- Its value is easy to understand
- You do not need to browse a rewards catalogue
- It can directly reduce your credit-card cost
- Redemption is often simpler
- You do not need to find a suitable product or travel booking
For people who want a simple reward with predictable value, cashback can be the better option.
What Are Credit Card Reward Points?
Reward points are units earned when you make eligible purchases with your credit card.
For example:
2 points per ₹100 spent
If you spend:
₹50,000
you may earn:
1,000 points
But those 1,000 points are not automatically worth ₹1,000.
Their value depends on the card’s redemption rules.
A point might be worth:
₹0.10
₹0.25
₹0.50
₹1
or another amount depending on the card and redemption method.
HDFC Bank’s published documents illustrate how redemption value can differ across cards, including examples ranging from ₹0.10 to ₹1 per point.
This is why reward points must always be converted into rupee value before comparing them with cashback.
Cashback vs Reward Points: The Biggest Difference
The simplest distinction is:
Cashback = Value is usually easy to calculate
Reward Points = Value depends on how you redeem them
Suppose two cards both advertise a reward equivalent to 2%.
Card A
Gives:
2% cashback
Your ₹10,000 spending produces:
₹200
Card B
Gives:
10 reward points per ₹100
Suppose each point is worth:
₹0.10
Then:
₹10,000 ÷ ₹100 = 100 reward units
100 × 10 points = 1,000 points
1,000 × ₹0.10 = ₹100
Despite the impressive-looking “10 points” figure, the actual reward is only 1%.
This is why the number of points alone means very little.
How to Calculate Reward Point Value
Use this formula:
Reward Value = Number of Points × Redemption Value per Point
Then calculate:
Effective Reward Rate = Reward Value ÷ Eligible Spending × 100
Example
Suppose you earn:
5,000 points
and can redeem them for:
₹2,500
Your point value is:
₹2,500 ÷ 5,000 = ₹0.50 per point
Now suppose you earned those points from:
₹1,00,000 spending
Your effective reward rate is:
₹2,500 ÷ ₹1,00,000 × 100 = 2.5%
Now you can compare that 2.5% directly with a cashback card.
Cashback vs Reward Points: Which Gives More Value?
There is no universal winner.
A cashback card is usually better when:
- You want simplicity
- You prefer statement credit
- You do not travel frequently
- You do not want to optimise redemption
- The cashback rate is genuinely competitive
A reward-point card may be better when:
- You redeem points for high-value travel
- The card offers strong transfer partners
- You receive a better redemption value for certain categories
- You can use milestone rewards
- You understand the programme well
Reward Points Can Sometimes Be Worth More
This is the main reason some experienced credit-card users prefer reward points.
Suppose:
10,000 points
can be redeemed for:
₹5,000 cashback
That means:
₹0.50 per point
But suppose the same 10,000 points can be used for a flight or hotel booking worth:
₹8,000
Then the point value becomes:
₹0.80 per point
Your effective reward value is now significantly higher.
However, you should compare against the actual cash price you would have paid, not an inflated catalogue price.
Cashback Is Better for Simplicity
Imagine you spend:
₹40,000 per month
and your cashback rate is:
2%
Monthly cashback:
₹800
Annual cashback:
₹800 × 12 = ₹9,600
You do not need to think about:
- Redemption catalogues
- Voucher availability
- Point transfers
- Travel dates
- Expiry
- Product prices
The benefit is straightforward.
For many cardholders, this simplicity has genuine value.
Reward Points Are Better for Strategic Spending
Reward-point cards can become more valuable when your spending matches the card’s bonus categories.
For example, a card may provide:
- Higher rewards on travel
- Higher rewards on dining
- Higher rewards on online shopping
- Lower rewards on general spending
Some cards also provide milestone bonuses after reaching specified spending thresholds.
HDFC Bank’s current card terms, for example, include category-specific earning rates, monthly caps and exclusions for several transaction types.
This means the headline reward rate is often not the rate you actually earn on every rupee spent.
The Importance of Spending Caps
This is one of the biggest differences between marketing claims and actual rewards.
Suppose a card advertises:
5% reward rate
but caps the benefit at:
₹1,000 per month
Once you cross the eligible spending threshold, the effective reward rate falls.
Example
Suppose 5% cashback applies only up to:
₹20,000 spending
Maximum cashback:
₹1,000
If you spend:
₹50,000
the effective reward rate becomes:
₹1,000 ÷ ₹50,000 × 100 = 2%
So a lower flat-rate cashback card could actually be better for a high-spending user.
Exclusions Matter Too
Credit cards frequently exclude certain transactions from rewards.
Potential exclusions can include:
- Fuel
- Rent
- Government payments
- Wallet loading
- EMI transactions
- Some education payments
- Cash advances
- Fees and charges
The exact exclusions vary by card.
For example, HDFC Bank’s published terms currently show exclusions and caps affecting categories such as rent, government payments, fuel, EMI and some education-related transactions on particular cards.
Therefore, calculate your rewards using eligible spending, not total credit-card spending.
Cashback vs Reward Points and Annual Fee
This is another factor many people ignore.
Suppose:
Card A
Annual fee:
₹1,000
Annual cashback:
₹8,000
Net reward:
₹7,000
Card B
Annual fee:
₹3,000
Annual reward value:
₹15,000
Net reward:
₹12,000
Card B is more expensive but still gives greater net value.
Now suppose Card B gives only ₹10,000 in annual rewards.
Its net benefit becomes:
₹7,000
Both cards are now equivalent.
So always calculate:
Net Annual Benefit = Reward Value − Annual Fee − Other Relevant Costs
Reward Redemption Fees
Reward points can come with a hidden cost: redemption fees.
For example, HDFC Bank’s published terms for some cards state that cashback redemption may have no handling charge while redemption through certain reward catalogues can attract a fee.
Even a ₹99 or ₹149 fee can matter if you redeem small amounts frequently.
If you have:
₹500 reward value
and pay:
₹99 redemption fee
your effective benefit falls to:
₹401
That is almost a 20% reduction in value.
Reward Point Expiry
Some reward programmes have expiry rules.
For example, one HDFC Bank card document states that unredeemed CashPoints can expire after two years of accumulation.
This means reward points are not always equivalent to permanently stored money.
Cashback is often easier to use before it becomes irrelevant.
Always check:
- Expiry period
- Minimum redemption requirement
- Redemption fee
- Maximum redemption
- Eligible redemption categories
Cashback vs Reward Points for Travel
This is where reward points can have a major advantage.
Frequent travellers may be able to redeem points for:
- Flights
- Hotels
- Travel vouchers
- Airline/hotel programmes
If the redemption value is high, reward points can outperform a simple cashback card.
For example:
₹10,000 cashback
versus
10,000 points worth ₹15,000 in genuine travel value
The rewards card is clearly more valuable.
But the ₹15,000 figure must represent a real saving.
You should not book an expensive hotel simply because points make it appear discounted.
Cashback vs Reward Points for Everyday Shopping
For regular purchases such as:
- Groceries
- Utility bills
- Online shopping
- Fuel
- Dining
cashback is often easier to evaluate.
If you get:
2% cashback
then you know exactly what you are earning on eligible spending.
With points, the result depends on redemption.
Cashback vs Reward Points for High Spenders
High spenders should pay special attention to caps.
A card with:
10% rewards capped at ₹1,000
can actually be less useful than a card with:
2% cashback without a comparable cap
when your monthly eligible spending is high.
Example
Card A:
10% × ₹10,000 = ₹1,000 maximum reward
Card B:
2% × ₹50,000 = ₹1,000
If you spend ₹1 lakh:
Card A remains capped at ₹1,000.
Card B could produce ₹2,000 if its terms allow the full amount.
The card with the lower advertised reward rate may therefore generate more actual value.
Cashback vs Reward Points for Low Spenders
For low and moderate spenders, simple cashback can also be attractive because annual fees can easily consume rewards.
Suppose you spend:
₹10,000 per month
and earn:
1.5% cashback
Annual spending:
₹1.2 lakh
Annual cashback:
₹1,800
If the card costs:
₹1,500 per year
your net reward is only:
₹300
A no-fee card with a slightly lower reward rate could be more valuable.
Reward Points and Milestone Benefits
Some cards provide bonuses when you reach an annual or quarterly spending target.
For example:
Spend ₹1 lakh → Bonus reward
This can increase the effective reward rate.
But milestone rewards can also encourage unnecessary spending.
Never spend ₹20,000 extra just to receive a ₹2,000 reward.
You have effectively spent ₹20,000 to “earn” ₹2,000.
The best credit-card strategy is to use the card for expenses you would make anyway.
Credit Card Rewards and EMI Transactions
EMI transactions deserve special attention.
Some credit cards do not award normal reward points on EMI transactions, while others may provide reduced or specific treatment.
HDFC Bank’s current terms, for example, state that EasyEMI transactions do not accrue reward points on certain cards, and points can also be reversed when transactions are converted to SmartEMI under specified terms.
Therefore, check whether your major spending is likely to happen through EMI.
A card that looks excellent for normal purchases may offer poor value for EMI-heavy spending.
Cashback vs Reward Points: Which Is Better for Beginners?
Cashback is generally easier for beginners.
Why?
Because you can calculate:
₹10,000 spend × 2% = ₹200
There is no need to understand point valuation.
Reward cards can be excellent, but you need to learn:
- Earning rate
- Redemption value
- Caps
- Exclusions
- Expiry
- Transfers
- Fees
For someone who does not want to manage all this, simple cashback can be more practical.
Which Is Better for Frequent Travellers?
Reward points can be better, particularly when the card offers valuable travel redemptions or transfer partners.
However, compare the real value.
Use:
Point Value = Actual Travel Value ÷ Points Required
Then compare it against cashback.
Which Is Better for Online Shoppers?
This depends on the card.
A cashback card with elevated rewards for online spending may be better for someone who wants direct savings.
A reward-point card can be better if its points can be redeemed at a significantly higher value on the platforms you already use.
Which Is Better for People Who Want Simplicity?
Cashback wins.
There is little optimisation required.
For many consumers, the best financial product is not the one with the highest theoretical reward.
It is the one they can use correctly without losing benefits through:
- Expiry
- Missed redemption
- Caps
- Unwanted purchases
- Annual fees
How to Calculate the Real Reward Rate
Use this formula:
Effective Reward Rate = Net Reward Value ÷ Eligible Spending × 100
Where:
Net Reward Value = Redemption Value − Redemption Fees − Relevant Costs
Example
Annual eligible spending:
₹6 lakh
Reward points earned:
30,000
Redemption value:
₹15,000
Redemption fees:
₹500
Annual card fee:
₹1,000
Net annual benefit:
₹15,000 − ₹500 − ₹1,000 = ₹13,500
Effective net reward rate:
₹13,500 ÷ ₹6,00,000 × 100 = 2.25%
Now you have a meaningful number to compare with a cashback card.
Cashback vs Reward Points: What Should You Check Before Choosing?
Before applying for a card, check:
- Actual Reward Rate
Do not rely on the headline number.
- Eligible Categories
See what earns rewards and what does not.
- Monthly/Quarterly Caps
A high reward rate with a low cap may not suit you.
- Redemption Value
Know the actual rupee value of one point.
- Redemption Fees
Check for processing or handling charges.
- Expiry
Understand when unused points expire.
- Annual Fee
Calculate the fee against expected yearly rewards.
- Spending Pattern
Choose according to how you already spend—not how you wish you spent.
Cashback vs Reward Points: Example
Suppose you spend:
₹50,000 per month
Cashback Card
Reward rate:
2%
Annual cashback:
₹50,000 × 12 × 2%
= ₹12,000
Annual fee:
₹1,000
Net:
₹11,000
Reward Card
Annual spending:
₹6 lakh
Points earned:
60,000
Effective redemption value:
₹0.25 per point
Reward value:
₹15,000
Annual fee:
₹2,500
Redemption costs:
₹500
Net benefit:
₹12,000
In this illustration, the reward-point card wins by:
₹1,000
But if the cardholder redeems those points poorly at only ₹0.15 per point, the calculation changes dramatically.
This is why redemption strategy is as important as earning rate.
Cashback vs Reward Points: Advantages and Disadvantages
Cashback Advantages
- Simple
- Transparent
- Easy to value
- Generally flexible
- Suitable for everyday spending
- Little effort required
Cashback Disadvantages
- Often has category caps
- Exclusions may apply
- May have lower upside than premium reward programmes
- Some cashback systems use points rather than immediate cash
Reward Points Advantages
- Can provide higher value through travel
- Multiple redemption options
- Milestone rewards
- Transfer opportunities on some cards
- Potentially higher effective reward rate
Reward Points Disadvantages
- Point value varies
- Redemption can be complicated
- Expiry may apply
- Caps and exclusions are common
- Redemption fees may reduce value
- Poor redemption can destroy the apparent advantage
Final Verdict
For most people who want simple, predictable credit-card savings, cashback is the easier and often more practical benefit.
For people who are willing to actively manage their credit-card rewards, reward points can be more valuable, particularly when redeemed for high-value travel or other benefits.
The best choice ultimately depends on your spending pattern.
Choose Cashback When:
- You want simplicity
- You prefer direct savings
- You do not travel often
- You want easy reward valuation
- You do not want to manage reward programmes
Choose Reward Points When:
- You travel frequently
- You understand redemption values
- You can use milestone benefits
- You redeem points strategically
- The card has strong transfer/redemption options
The most important rule is:
Never choose a credit card because its reward number looks big.
A card offering “10 points per ₹100” is not necessarily better than one offering “2% cashback.”
Always calculate:
Actual reward value ÷ actual eligible spending
Then subtract:
Annual fee + redemption costs + other relevant charges
That gives you the real benefit.
In many cases, a simple 2% cashback card can beat a complicated rewards card because the cashback is easy to use and has fewer opportunities for value leakage. In other cases, a well-managed reward-point card can deliver substantially more value.
The best credit card is therefore the one that matches your existing spending behaviour and gives you the highest net reward—not the most impressive advertisement.
FAQs
Is cashback better than reward points?
Not always. Cashback is simpler and easier to value, while reward points can provide higher value when redeemed strategically, especially for travel.
How much is one credit-card reward point worth?
There is no universal value. It depends on the card and redemption method. Some bank programmes use different conversion values across cards and redemption options.
Do reward points expire?
Some do. Expiry periods vary by card and issuer. For example, certain HDFC Bank card terms specify expiry of unredeemed points after a stated period. Always check your card’s current terms.
Are cashback credit cards always better for beginners?
They can be easier to manage because the reward value is more straightforward. But a reward-point card may be better if the beginner has spending patterns that match strong reward categories.
Why do credit cards have reward caps?
Caps control the maximum rewards a card issuer will provide in a particular category or period. A card with a high advertised reward rate can therefore have a much lower effective rate after reaching the cap. Current bank terms show that monthly and category-specific caps are common.
How do I know whether a reward card is actually worth it?
Calculate the card’s net annual value:
Total redemption value − annual fee − redemption fees − other relevant costs
Then divide that amount by your eligible annual spending. Compare the resulting effective percentage with cashback cards.