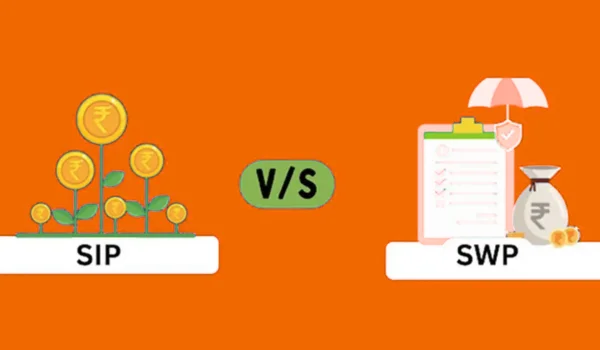
SIP and SWP are not really competing investment products. They are two different ways of using mutual funds for different financial goals.
A Systematic Investment Plan (SIP) helps you invest a fixed amount regularly and build wealth over time. A Systematic Withdrawal Plan (SWP) allows you to withdraw a specified amount periodically from an existing mutual fund investment. AMFI describes SIP as a periodic investment method, while SEBI investor material recognises both SIP and SWP as systematic ways to invest or redeem mutual-fund units.
So, asking “SIP vs SWP: which is better?” is a little like asking saving vs spending: which is better? The answer depends on your stage of life and financial goal.
Quick Comparison
| Factor | SIP | SWP |
| Full Form | Systematic Investment Plan | Systematic Withdrawal Plan |
| Main Purpose | Wealth creation | Regular withdrawals |
| Money Flow | Investor → Mutual Fund | Mutual Fund → Investor |
| Suitable For | Working/investing phase | Income/withdrawal phase |
| Corpus Needed | Not required initially | Existing corpus required |
| Market Benefit | Can average purchase prices over time | Remaining corpus can stay invested |
| Regular Income | No | Yes, through periodic redemptions |
| Main Risk | Market volatility | Corpus depletion/sequence risk |
| Ideal Goal | Long-term wealth building | Retirement or regular cash flow |
What Is SIP?
SIP allows you to invest a fixed amount into a mutual fund at regular intervals, commonly monthly. AMFI notes that SIPs can help with disciplined investing and rupee-cost averaging, rather than requiring the investor to make a large lump-sum investment at one time.
For example, you might invest:
₹10,000 every month
instead of investing ₹1.2 lakh at the beginning of the year.
When the market is lower, the same SIP amount buys more units. When the market is higher, it buys fewer units. Over time, this creates a systematic investment process.
Why People Use SIP
SIP can be useful for:
- Building a retirement corpus
- Creating a long-term investment portfolio
- Funding children’s education
- Saving for long-term goals
- Building wealth gradually
SIP does not guarantee returns. The value of the mutual fund depends on the underlying investments and market performance.
What Is SWP?
SWP allows an investor to withdraw a specified amount from an existing mutual-fund investment at regular intervals.
For example, suppose you have:
₹30 lakh invested
and set up:
₹25,000 monthly SWP
The mutual fund periodically redeems enough units to provide the withdrawal amount. The remaining investment stays in the fund and can continue to fluctuate with the market. SEBI-filed scheme documents describe SWP as a facility for periodic withdrawal and note its suitability for investors seeking regular inflows.
This is why SWP is commonly considered during retirement or other income-requiring phases.
SIP vs SWP: The Biggest Difference
The simplest difference is:
SIP = Money goes into the investment
SWP = Money comes out of the investment
SIP is primarily an accumulation strategy.
SWP is primarily a distribution strategy.
Therefore, they serve opposite cash-flow directions.
SIP for Wealth Creation
SIP is generally more suitable when you have regular income and want to build a corpus over many years.
Suppose a person invests:
₹15,000 per month
for:
20 years
At an assumed annual return of 12%, the future value would be approximately ₹1.50 crore.
The total amount invested would be:
₹15,000 × 12 × 20 = ₹36 lakh
The remaining amount represents assumed investment growth.
Important
The 12% return is only a mathematical illustration, not a guaranteed mutual-fund return. Actual market returns can be significantly different.
SWP for Regular Income
Now consider someone who has already accumulated a large corpus.
Suppose the investor has:
₹50 lakh
and wants:
₹30,000 per month
through SWP.
The annual withdrawal is:
₹30,000 × 12 = ₹3.6 lakh
That is equivalent to an initial withdrawal rate of:
₹3.6 lakh ÷ ₹50 lakh = 7.2% per year
Whether this is sustainable depends on investment returns, inflation, taxes, market volatility, withdrawal increases and the length of the withdrawal period.
A high withdrawal rate can gradually reduce the corpus, especially when markets perform poorly.
SIP vs SWP for Different Financial Goals
| Financial Goal | Better Approach |
| Build retirement corpus | SIP |
| Build long-term wealth | SIP |
| Invest monthly from salary | SIP |
| Create regular retirement cash flow | SWP |
| Generate periodic withdrawals from corpus | SWP |
| Preserve and gradually use a corpus | SWP |
| Accumulation + later income | SIP followed by SWP |
This last point is particularly important.
SIP and SWP Can Be Used Together
You do not necessarily have to choose one forever.
A common financial journey can look like:
Working years → SIP → Wealth accumulation → Retirement corpus → SWP
For example:
Age 30–55: SIP
Age 55 onward: SWP
This creates a transition from accumulation to distribution.
Which Is Better for Wealth Creation?
For wealth accumulation, SIP is generally the more relevant strategy.
It allows you to keep adding money to your investment over time. The longer the investment period, the more opportunity there is for compounding to work.
SWP, by definition, takes money out of the investment.
Therefore, an SWP is usually not the tool you would choose when the main goal is to maximise the accumulation of a corpus.
Which Is Better for Regular Income?
For regular withdrawals from a mutual-fund corpus, SWP is the more appropriate mechanism.
Instead of redeeming a large amount at one time, an investor can schedule periodic withdrawals.
For example:
₹20,000 every month
or
₹60,000 every quarter
depending on the scheme’s available facilities and the investor’s requirements.
SEBI-filed scheme documents explicitly describe SWP as a facility for periodic withdrawals from mutual-fund investments.
However, SWP is not the same as earning fixed interest.
The withdrawal comes from your investment corpus through redemption of units.
Is SWP Guaranteed Income?
No.
This is one of the most important things to understand.
Suppose your portfolio earns less than the amount you withdraw.
Your corpus can decline.
For example, if your portfolio returns only 5% during a particular period but you withdraw an amount equivalent to 8% annually, the difference can come from the original corpus.
During market declines, the impact can be even more serious because you may be selling more units to generate the same cash withdrawal.
Sequence of Returns Risk
SWP investors should understand sequence of returns risk.
Imagine two retirees have identical average long-term returns.
Investor A experiences strong returns during the first few years.
Investor B experiences a significant market fall soon after starting withdrawals.
Even if the long-term average return eventually becomes similar, Investor B may end up with a smaller corpus because units were sold during the market decline.
This is one reason withdrawal planning should consider market volatility rather than assuming a constant annual return.
SIP vs SWP During Market Volatility
SIP During a Falling Market
A falling market can mean that your fixed SIP amount purchases more units.
This is one reason SIP is often associated with rupee-cost averaging.
However, falling prices also mean your existing portfolio value may decline.
SWP During a Falling Market
The situation is different.
You are selling units while the portfolio value is down.
If you continue withdrawing the same rupee amount, you may have to redeem more units.
This can increase pressure on the remaining corpus.
SIP vs SWP and Tax
Tax treatment is another important difference.
SIP Tax
Each SIP instalment is a separate investment. When those units are eventually redeemed, the capital gain is determined according to the relevant holding period and type of mutual fund.
SWP Tax
An SWP is effectively a series of redemptions. The entire withdrawal is not automatically treated as profit.
A portion represents the cost of the units being redeemed, while the remaining portion may represent capital gains.
The tax depends on factors including:
- Type of mutual fund
- Purchase date
- Holding period
- Capital gain
- Applicable tax provisions
For equity-oriented funds, the current framework taxes short-term capital gains under Section 111A at 20% for transfers on or after July 23, 2024, while qualifying long-term gains under Section 112A above the ₹1.25 lakh annual threshold are taxed at 12.5%.
Other mutual-fund categories can follow different tax rules, so investors should not apply equity-fund tax rates to every SWP.
Is SWP More Tax-Efficient Than Interest?
It can be tax-efficient in some situations, but this depends on the investor and the underlying fund.
With SWP, the tax calculation applies to the capital gain portion of redeemed units, rather than automatically taxing the entire withdrawal as interest income.
But this does not mean every SWP is automatically tax-efficient.
The fund category, holding period, gains and applicable tax rules all matter.
SIP vs SWP: Advantages and Disadvantages
SIP Advantages
- Encourages disciplined investing
- Suitable for regular income earners
- Helps build a corpus gradually
- Avoids depending entirely on one investment date
- Can be useful for long-term goals
SIP Disadvantages
- Does not provide regular income from the investment
- Market-linked returns can fluctuate
- Requires continuous cash flow for ongoing investments
- Long-term wealth is not guaranteed
SWP Advantages
- Provides scheduled cash withdrawals
- Useful for retirement income planning
- Can allow the remaining corpus to stay invested
- Provides flexibility in choosing withdrawal amounts and frequency
- Can be used with different mutual-fund strategies depending on investor needs
SEBI-filed scheme documents state that SWP allows a specified sum to be withdrawn periodically while the remaining investment continues in the scheme.
SWP Disadvantages
- Can reduce the investment corpus
- Returns are not guaranteed
- Market falls can hurt sustainability
- Excessive withdrawals can exhaust the corpus
- Tax and exit-load rules may apply
SEBI’s investor material also notes that mutual-fund redemptions can be subject to exit load depending on the scheme and timing.
SIP vs SWP: Which Is Better for Retirement?
A retirement plan often needs both.
Before Retirement
SIP can help accumulate the retirement corpus.
After Retirement
SWP can help convert that corpus into a regular cash flow.
For example:
Age 30–40: ₹10,000 monthly SIP
Age 40–50: Increase SIP as income rises
Age 50–60: Continue accumulation and rebalance portfolio
Retirement: Begin planned SWP
This is only an example; the exact strategy depends on the investor’s age, corpus, expenses and risk tolerance.
SIP vs SWP Example
Consider two investors.
Investor A: SIP
Invests:
₹20,000 per month
for 20 years.
At an assumed 12% annual return, the corpus could grow to approximately ₹1.92 crore.
Total contribution:
₹48 lakh
Investor B: SWP
Starts with:
₹1 crore corpus
and withdraws:
₹50,000 per month
Annual withdrawal:
₹6 lakh
Initial withdrawal rate:
6% per year
Investor B receives regular cash flow, but the sustainability of that income depends on investment returns, inflation, taxes and future withdrawal changes.
These examples show why comparing SIP and SWP purely on “returns” is misleading. They solve different financial problems.
Can You Start an SWP Without SIP?
Yes.
You do not need to have built your entire corpus through SIP.
An investor may have accumulated money through:
- Lump-sum investment
- Sale of property
- Business income
- Inheritance
- Retirement benefits
- Previous investments
That corpus can potentially be used for an SWP, subject to the mutual-fund scheme’s rules.
Can You Stop or Change an SIP or SWP?
Generally, these are flexible facilities, but the exact procedure and minimum amounts vary by scheme.
SEBI and mutual-fund documentation provide for SIP and SWP facilities under scheme-specific conditions. Also, in July 2026, SEBI extended the facility for creating standing instructions for SWP and STP for mutual-fund units held in demat form.
Investors should therefore check the specific mutual fund’s current terms for:
- Minimum amount
- Frequency
- Number of instalments
- Exit load
- Cancellation process
- Cut-off rules
Which Is Better: SIP or SWP?
The answer depends on your financial stage.
For wealth creation: SIP is generally better suited.
For regular withdrawals: SWP is generally better suited.
For retirement planning: SIP can be used to build the corpus, followed by SWP to generate withdrawals.
So the better question is not:
“SIP vs SWP — which is best?”
It is:
“Am I trying to build wealth or use the wealth I have already built?”
Final Verdict
SIP and SWP should not be treated as two competing investment products.
SIP is mainly for accumulation.
SWP is mainly for distribution.
A young investor with a regular salary may use SIP to build long-term wealth. An investor who already has a substantial corpus and needs regular cash flow may consider SWP.
For retirement, the two can work together:
SIP → Build Corpus → SWP → Generate Regular Income
The most important point is that SWP does not create guaranteed income. The money comes from redeeming mutual-fund units, and continued withdrawals can reduce the corpus, particularly during poor market periods.
Similarly, SIP does not guarantee wealth creation because mutual funds are market-linked investments.
Before choosing either strategy, consider your investment horizon, risk tolerance, corpus size, monthly expenses, inflation, tax position and withdrawal requirement.
FAQs
- Is SIP better than SWP?
Neither is universally better. SIP is designed primarily for regular investing and wealth accumulation, while SWP is designed for periodic withdrawals from an existing investment.
- Can I use SIP and SWP together?
Yes. A common long-term approach is to use SIP while building a corpus and then use SWP after reaching the income or retirement stage.
- Is SWP income guaranteed?
No. SWP provides scheduled withdrawals, but the underlying mutual fund remains market-linked. Excessive withdrawals or poor market performance can reduce the corpus.
- Is SWP taxable?
SWP withdrawals can have tax implications because units are redeemed. Tax is generally based on the capital-gain rules applicable to the redeemed units and the type of mutual fund. For equity-oriented funds, qualifying LTCG above ₹1.25 lakh is currently taxed at 12.5%, while specified STCG is taxed at 20% for applicable transfers.
- How much should I withdraw through SWP?
There is no universally safe amount. The withdrawal should be assessed against the corpus, expected returns, inflation, taxes and investment horizon. A higher withdrawal rate can increase the risk of exhausting the corpus.
- Which is better for retirement: SIP or SWP?
Both can have a role. SIP can help build the retirement corpus during working years, while SWP can convert that corpus into periodic withdrawals after retirement.