When you have extra money after paying your monthly expenses, one common financial question is:
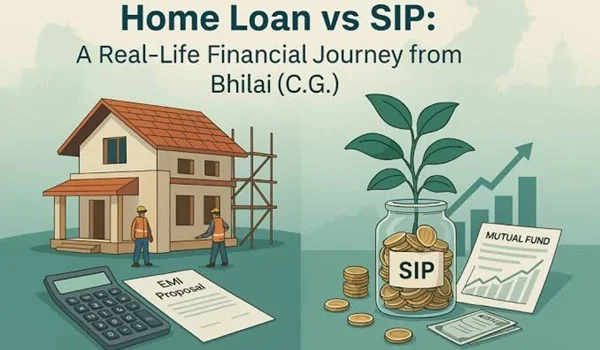
Should you use the money to prepay your home loan or invest it through an SIP?
Both choices can improve your financial position, but they work differently.
A home-loan prepayment gives you a relatively certain benefit by reducing future interest payments. An SIP puts your money into market-linked investments that can potentially generate higher long-term returns, but those returns are not guaranteed.
For 2026, the decision also needs to consider tax treatment, your home-loan interest rate, remaining loan tenure, investment horizon and risk tolerance. Under the current tax rules, the treatment of home-loan interest differs between the old and new tax regimes. For a self-occupied property, the old regime allows a Section 24(b) interest deduction of up to ₹2 lakh subject to conditions, while interest on a self-occupied property is not deductible under the new regime.
So, the real question is not simply “Loan vs SIP?” It is:
What is the best use of each additional rupee after considering the guaranteed saving from debt reduction versus the uncertain return from investing?
Quick Comparison
| Factor | Home Loan Prepayment | SIP |
| Main Goal | Reduce debt | Build wealth |
| Return | Effectively saves loan interest | Market-linked |
| Return Certainty | High | Not guaranteed |
| Risk | Low | Depends on investment |
| Liquidity | Money becomes part of home equity | Investment can generally be redeemed |
| Tax Impact | Can reduce future interest deduction | Depends on investment type |
| Best Horizon | Any, especially high-rate debt | Usually long term |
| Emotional Benefit | Lower debt burden | Growing investment corpus |
| Market Risk | None on amount prepaid | Yes |
| Best For | Debt reduction | Long-term wealth creation |
What Is Home Loan Prepayment?
Home-loan prepayment means paying an additional amount over and above your scheduled EMI.
For example, suppose your monthly EMI is:
₹40,000
and you receive a bonus of:
₹2 lakh
You can use the ₹2 lakh to reduce the outstanding principal.
This can reduce either:
- Your remaining loan tenure
- Your future interest burden
- Or both, depending on how the lender applies the prepayment and how you restructure the loan.
For floating-rate non-business loans to individual borrowers, RBI’s framework generally prohibits banks from charging foreclosure/prepayment penalties, and RBI has also extended similar protections through applicable directions for NBFC/HFC cases. Exact applicability should be checked against the loan type and lender terms.
What Is SIP?
A Systematic Investment Plan (SIP) is a method of investing a fixed amount regularly into a mutual fund.
For example:
₹15,000 per month
can be invested through SIP into a suitable mutual-fund scheme.
The money is invested in market-linked assets according to the selected fund.
Unlike prepaying a loan, SIP does not provide a guaranteed return.
Depending on the investment, the portfolio may generate:
- Positive returns
- Low returns
- Negative returns
over different periods.
The Biggest Difference
The easiest way to understand the comparison is:
Home Loan Prepayment = Guaranteed interest saving
SIP = Potential investment growth
Suppose your home loan interest rate is 8%.
When you prepay ₹1 lakh, you effectively avoid paying future interest on that ₹1 lakh, subject to the loan’s amortisation and the timing of the prepayment.
That saving is relatively predictable.
If you invest the same ₹1 lakh through an equity SIP or other market-linked investment, you may earn:
6%, 8%, 10%, 12% or more — or potentially experience losses over shorter periods.
Therefore, SIP needs to earn sufficiently more than the effective cost of the loan to make the investment-first approach financially attractive.
Home Loan Prepayment vs SIP: A Simple Example
Suppose you have:
- Outstanding home loan: ₹50 lakh
- Interest rate: 8%
- Remaining tenure: 15 years
- Extra money available: ₹5 lakh
You have two choices.
Option A: Prepay ₹5 Lakh
The ₹5 lakh reduces your loan principal.
The benefit is lower future interest.
Option B: Invest ₹5 Lakh
You could invest the amount into a suitable mutual fund strategy.
If the investment grows at a hypothetical 12% annualised return, it could become significantly larger over a long period.
But the 12% return is only an assumption.
The investment could perform below that, especially over shorter periods.
This is why comparing:
8% loan rate vs 12% expected SIP return
is not enough.
You must also consider:
- Taxes
- Investment risk
- Loan tenure
- Compounding
- Liquidity
- Behaviour
- Market volatility
Guaranteed Saving vs Expected Return
This is perhaps the most important concept.
Prepayment
If your loan costs you 8%, reducing the outstanding principal gives you an economic benefit broadly linked to avoiding that 8% borrowing cost.
SIP
If your investment has an expected long-term return of 12%, that 12% is not guaranteed.
So the comparison is actually:
Certain debt saving vs uncertain investment return
This means a risk-averse investor may prefer prepayment even when the expected SIP return is higher.
When Home Loan Prepayment Makes More Sense
Prepayment can be attractive when:
- Your Loan Interest Rate Is High
If your home loan rate is relatively high, eliminating that interest cost can be financially valuable.
- You Have a Shorter Remaining Tenure
When the loan is already well into its repayment period, the exact benefit depends on the amortisation schedule and how much interest remains.
- You Are Risk-Averse
If market volatility makes you uncomfortable, a guaranteed debt reduction may be more appealing.
- You Want Financial Freedom
Becoming debt-free can reduce financial stress and improve monthly cash flow.
- You Already Have Investments
If you already have a substantial SIP portfolio, putting additional money toward the loan can improve diversification between financial assets and debt reduction.
When SIP Can Make More Sense
SIP may be more attractive when:
- You Have a Long Investment Horizon
Equity-oriented investments are generally more suitable when you can remain invested through market cycles.
- Your Home Loan Rate Is Relatively Low
If your borrowing cost is low and you have a high risk tolerance, investing may offer greater long-term growth potential.
- You Need Liquidity
Money invested in financial assets is generally easier to access than money used to repay your home loan.
Once you prepay your home loan, the money becomes tied up in the property unless you later refinance or borrow against it.
- You Are Building a Retirement Corpus
Long-term SIP investing can help create a separate financial asset pool rather than putting most of your wealth into your home.
- You Have a Strong Emergency Fund
You should not use all your liquid savings for prepayment.
An emergency reserve should generally come before aggressive debt repayment or investing.
Loan Interest Rate vs Expected SIP Return
This comparison can be useful as a starting point.
| Situation | Possible Preference |
| Loan 9%+, low risk tolerance | Prepayment may be attractive |
| Loan 7%–8%, long horizon | Either can make sense |
| Loan 6%–7%, high risk tolerance | SIP may be worth considering |
| Very short investment horizon | Prepayment may be preferable |
| 15–20+ year investment horizon | SIP can have stronger wealth-building potential |
These are general illustrations, not universal rules.
A 12% assumed SIP return should never be treated as a guaranteed benchmark.
The Role of Tax Benefits
Tax treatment can change the effective cost of your home loan.
Under the old tax regime, Section 24(b) allows a deduction for interest paid on a qualifying self-occupied home loan up to ₹2 lakh, subject to conditions. The Income Tax Department also recognises housing-loan principal as part of the Section 80C framework, whose combined limit is ₹1.5 lakh.
However, the new tax regime does not allow the Section 24(b) deduction for interest on a self-occupied property.
This means your effective cost of borrowing can differ based on which tax regime you use.
Example
Suppose your home loan interest rate is:
8%
If you receive a meaningful tax benefit from the interest deduction, the effective after-tax cost may be lower than 8%.
If you are under the new regime and your self-occupied property does not qualify for that deduction, that tax benefit may not be available.
Therefore, compare after-tax loan cost, not just the advertised interest rate.
Home Loan Prepayment vs SIP for the New Tax Regime
The new tax regime can change the calculation significantly.
For a self-occupied property, the Income Tax Department states that interest on borrowed capital under Section 24(b) is not deductible under the new regime.
As a result, an investor using the new regime may have less reason to retain a home loan purely for its tax benefit.
However, this does not mean everyone should immediately prepay.
You should still compare:
Effective loan cost vs expected investment return + liquidity + risk
Should You Prepay or Reduce EMI?
When you make a prepayment, lenders may allow you to choose between:
Reduce EMI
Your monthly payment becomes lower while the tenure may remain broadly similar.
Reduce Tenure
Your EMI may remain similar, but the loan ends earlier.
For someone focused on reducing total interest, tenure reduction can often be more powerful, because you stop paying interest sooner.
The exact effect depends on the lender and the way the prepayment is processed.
Example: Why Tenure Reduction Matters
Suppose you have a large outstanding loan and make a significant prepayment.
If you keep the EMI unchanged and reduce the remaining tenure, you continue paying the same monthly amount but clear the principal faster.
This can potentially reduce the total interest paid over the life of the loan.
If instead you reduce the EMI, you get immediate monthly cash-flow relief but may continue carrying the loan for longer.
So if your objective is:
Maximum interest saving → consider tenure reduction
If your objective is:
Lower monthly financial burden → consider EMI reduction
Should You Stop SIP to Prepay Home Loan?
Usually, there is no need to choose an extreme approach.
You can divide your extra cash.
For example:
₹20,000 extra per month
could become:
₹10,000 → Home loan prepayment
₹10,000 → SIP
This creates a middle path.
You continue reducing debt while also building financial assets.
This can be especially useful for investors who are uncomfortable making an all-or-nothing decision.
The Hybrid Strategy
A hybrid approach may be one of the most practical options.
For example:
Step 1
Maintain an emergency fund.
Step 2
Ensure adequate insurance protection.
Step 3
Continue a basic long-term SIP.
Step 4
Use additional bonuses and surplus cash for selective home-loan prepayments.
This approach gives you:
- Debt reduction
- Investment growth potential
- Liquidity
- Diversification
You do not have to make the entire decision based on one variable.
Home Loan Prepayment vs SIP and Inflation
Inflation changes the way you should think about debt.
A long-term home loan is repaid with future rupees, which will generally have lower purchasing power than today’s rupees.
At the same time, inflation can reduce the real value of investment returns.
This makes the comparison more nuanced.
A fixed home-loan rate can become less burdensome in real terms if income rises significantly over time.
But you should not rely on inflation alone to justify keeping a loan.
Your actual cash flow and interest rate matter more.
Home Loan Prepayment vs SIP: Liquidity
Winner: SIP
Once money has been used to prepay a home loan, it becomes home equity.
You generally cannot simply withdraw it when you need cash.
A mutual fund investment can usually be redeemed subject to the scheme’s terms and applicable exit loads.
Therefore, investing all surplus cash into home-loan prepayment can leave you asset-rich but cash-poor.
This is especially important for:
- Young families
- Self-employed people
- People with variable income
- People expecting major expenses
Home Loan Prepayment vs SIP: Risk
Prepayment
The financial benefit is relatively predictable.
SIP
The outcome is uncertain.
An equity-heavy SIP can experience large temporary declines.
For example, a ₹10 lakh portfolio falling 25% becomes:
₹7.5 lakh
That does not necessarily mean a permanent loss if you remain invested and the market recovers, but it can be difficult emotionally.
The home-loan prepayment has no equivalent market-price volatility.
Home Loan Prepayment vs SIP for Retirement
A common mistake is becoming completely debt-free but having very little retirement savings.
Imagine someone has:
- ₹80 lakh home
- ₹0 investment corpus
- No debt
versus someone with:
- ₹60 lakh home equity
- ₹20 lakh investment portfolio
- Some remaining loan
The second person may have greater financial liquidity despite having debt.
Therefore, retirement planning should not be sacrificed entirely for faster loan repayment.
Home Loan Prepayment vs SIP for Young Investors
A younger investor has a longer investment horizon.
That can make SIP more attractive because there is more time for compounding and for the investor to recover from market downturns.
However, younger investors also have many future financial commitments.
A balanced approach is often more practical than maximising either investment or prepayment.
Home Loan Prepayment vs SIP for Older Borrowers
For someone approaching retirement, reducing debt can become more important.
Why?
Because retirement income may be lower than salary income.
Entering retirement with a large EMI can create significant cash-flow pressure.
A person close to retirement may therefore prefer to:
Reduce outstanding loan → Lower fixed expenses → Protect retirement cash flow
The right approach still depends on investment corpus, pension, loan balance and monthly expenses.
Home Loan Prepayment vs SIP: Example With ₹5 Lakh
Suppose you receive a ₹5 lakh bonus.
Option A: Prepay
Loan interest rate:
8%
You reduce your outstanding principal by ₹5 lakh.
The economic benefit is the interest you avoid over the remaining life of the loan, subject to the amortisation schedule.
Option B: Invest
Suppose you invest ₹5 lakh and assume an annual return of:
12%
After 10 years, the hypothetical value would be around:
₹15.53 lakh
But the actual return could be much lower or higher.
The key question becomes:
Would you rather accept a certain loan-interest saving or take market risk for potentially higher wealth creation?
A Better Mathematical Approach
Instead of comparing:
Home Loan Rate = 8%
with
SIP Return = 12%
compare:
After-tax effective loan cost
against
Expected after-tax investment return
Then adjust for:
- Risk
- Liquidity
- Investment horizon
- Behaviour
- Emergency needs
A 4-percentage-point expected advantage may not be enough for someone who strongly dislikes investment risk.
A Practical Decision Rule
Consider prepayment more seriously when:
Loan rate is high + short horizon + low risk tolerance + adequate emergency fund
Consider SIP more seriously when:
Loan rate is moderate/low + long horizon + high risk tolerance + strong emergency fund
Consider doing both when:
You want debt reduction and wealth creation simultaneously.
One More Important Point: Don’t Ignore Emergency Savings
Before using extra money for either prepayment or SIP, maintain a suitable emergency fund.
Suppose you have:
₹10 lakh savings
and use the entire amount to prepay your loan.
Three months later, you face a major financial emergency.
You may have a valuable house but insufficient liquid cash.
This can force you to borrow again at a higher rate.
Therefore:
Emergency fund first → Insurance → Loan/investment optimisation
is often a more robust framework.
Home Loan Prepayment vs SIP: Pros and Cons
Home Loan Prepayment Advantages
- Reduces outstanding debt
- Saves future interest
- Provides a relatively certain financial benefit
- Can shorten loan tenure
- Reduces financial stress
- Can improve future monthly cash flow
Home Loan Prepayment Disadvantages
- Reduces liquidity
- Money becomes tied to home equity
- May reduce eligible future interest deductions under applicable tax rules
- Can result in over-concentration in real estate
- May reduce your ability to invest in growth assets
SIP Advantages
- Builds a separate financial corpus
- Higher long-term growth potential
- Keeps money relatively liquid
- Can diversify wealth outside real estate
- Useful for retirement and other long-term goals
SIP Disadvantages
- Returns are not guaranteed
- Market volatility
- Potential temporary or permanent losses depending on investment choice
- Requires discipline
- Can tempt investors to stop investing during market downturns
Which Is Better for You?
| Situation | Possible Choice |
| High home-loan rate | Prepayment |
| Very long investment horizon | SIP |
| Low risk tolerance | Prepayment |
| Strong risk tolerance | SIP |
| No emergency fund | Build emergency fund first |
| Near retirement | Prepayment may get priority |
| Young investor with long horizon | SIP may get more priority |
| Large existing investment corpus | More room for prepayment |
| Very large home-loan balance | Consider a hybrid |
| Need liquidity | SIP |
| Strong desire to become debt-free | Prepayment |
Final Verdict
There is no universal winner between home-loan prepayment and SIP.
Home-loan prepayment provides something powerful: a relatively certain saving on future borrowing costs.
SIP provides something equally important: the opportunity to build a separate, liquid, diversified investment corpus that can potentially grow faster than the effective cost of your loan.
For many people, the smartest answer is not 100% prepayment or 100% SIP.
A practical strategy can be:
Emergency Fund → Insurance → Continue SIP → Use surplus/bonuses for selective loan prepayment
The exact ratio depends on your home-loan interest rate, remaining tenure, tax regime, investment horizon and risk tolerance.
For 2026, tax regime matters particularly because the Income Tax Department confirms that the old regime can allow up to ₹2 lakh Section 24(b) deduction for interest on a qualifying self-occupied home loan, while the deduction is not available for self-occupied property under the new regime.
So before making a large prepayment, calculate the after-tax cost of your loan and compare it with a realistic, after-tax expected investment return—not an optimistic SIP assumption.
FAQs
Is it better to prepay a home loan or invest in SIP?
It depends on the loan interest rate, investment horizon, risk tolerance and tax position. Prepayment gives a more certain benefit, while SIP offers higher potential returns but with market risk.
Should I stop my SIP to repay my home loan faster?
Not necessarily. Completely stopping long-term investments may reduce your retirement corpus. A hybrid strategy, where part of the surplus goes toward prepayment and part toward SIP, can be more balanced.
Is home-loan prepayment tax-free?
Prepayment itself is not an investment return that needs to be taxed. Its benefit comes mainly from reducing future interest payments. However, reducing your loan can also affect the amount of interest eligible for any applicable tax deduction.
Is SIP return guaranteed to beat home-loan interest?
No. If your loan costs 8% and you assume a 12% SIP return, the 4% difference is not guaranteed. Mutual-fund investments can perform poorly or generate negative returns over some periods.
Should I prepay my home loan before retirement?
Often, reducing significant debt before retirement can improve cash flow and reduce financial pressure. However, you should also ensure that you have sufficient retirement investments and liquid savings.
Can I do both home-loan prepayment and SIP?
Yes. For many borrowers, this can be a practical approach. You can continue a regular SIP for long-term wealth creation while using bonuses or part of your surplus cash to reduce the loan principal.